
News Digest: Cat bond risk spreads fall to lowest level since 2017 as October tightening continues
November 16, 2026
Catastrophe bond risk spreads declined further in October, reaching their lowest level since 2017, according to data from Plenum Investments. The insurance risk spread of the outstanding cat bond market stood at 4.33% on 30 October, roughly 13% below the same time last year. The last comparable level was in August 2017.
The market’s overall coupon yield fell to 8.41%, from 8.74% on 25 September. That is about 4.5% lower year on year, a smaller decline than spreads alone because US money market rates were lower a year ago. Collateral yield contributes 4.08% of the total. Expected loss in the market rose to 2.55% from 2.25% a year earlier, which means investors are taking on slightly more risk. Return over expected loss slipped to 5.86% from 6.24% in September.
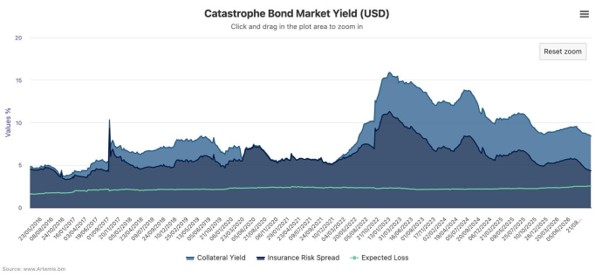
Plenum attributed the move to seasonal tightening during hurricane season. Spreads narrowed by a further 5% in October, but the pace is slowing. Tightening is expected to continue at a more moderate rate into November, before spreads start widening again in December.
The bigger question is how newer, lower-priced bonds issued in the current softer market will affect yields. With the pipeline building and Q4 looking like another strong issuance period, the effect should become clearer over the next month or two.
Despite lower pricing, returns remain well above the last soft market. When spreads hit their record low in 2016, total coupon yield fell to around 3.70%, and yield over expected loss was below 2%. Total returns in October ranged from 8.4% in USD to 7.0% in EUR and 4.2% in CHF. Investor appetite remains strong, as cat bonds continue to be seen as a diversifier with relatively uncorrelated returns.
End Notes